Home › Van delivery drivers · Updated
Van delivery driversVan delivery driver insurance for parcel work
Whether you drive someone else's van on a parcel round or deliver in your own, the insurance question is the same: whose policy covers you, and for what. Compare van delivery driver cover that matches the way you work.
Get started- Free to use
- No obligation to buy
- For employed and owner-driver parcel work
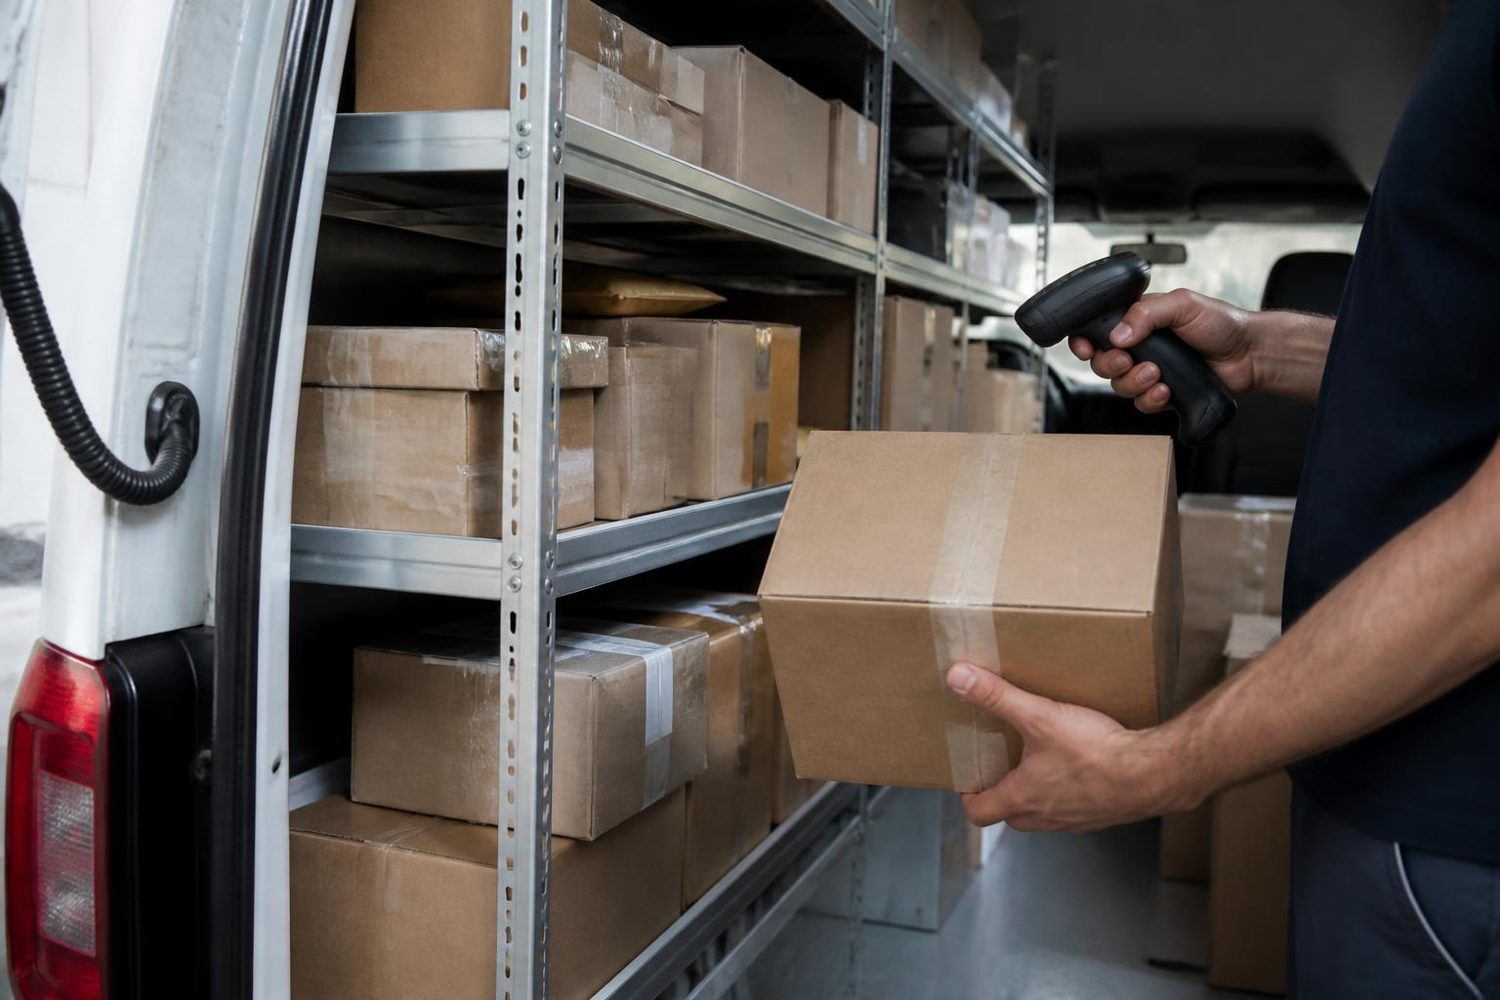
Van delivery driver insurance is hire and reward van cover for delivering parcels, and who arranges it depends on whose van you drive. If you drive a van provided by an employer or delivery firm, their policy usually covers you while you work. If you use your own van, you usually need your own policy with hire and reward use, plus any goods and liability cover your contract asks for.
- Specialist brokersCourier insurance brokers who arrange hire and reward cover every day.
- One short formTell us about the vehicle, the work and the drivers once.
- No obligationCompare the options you are offered and decide in your own time.
At a glance
- Who insures the van usually depends on who owns or provides it.
- Employed drivers in a company van are normally covered by the employer's policy.
- Drivers using their own van usually arrange their own hire and reward cover.
- Some delivery networks provide or offer insurance, and terms vary and change.
- An employer's policy may not cover personal use or your own belongings.
- Goods in transit and public liability may sit with you or the firm, depending on the contract.
Whose van you drive decides whose policy applies
Parcel delivery drivers fall into two broad groups. Some drive a van owned or leased by an employer or delivery firm. Others use their own van, owned, financed or rented, and deliver as self-employed drivers or subcontractors.
The van policy follows the vehicle. If the van is provided to you, the provider usually insures it. If the van is yours, the insurance is usually yours too. Knowing which group you are in is the first step to knowing what you need.
Driving a company van: what the employer's policy usually covers
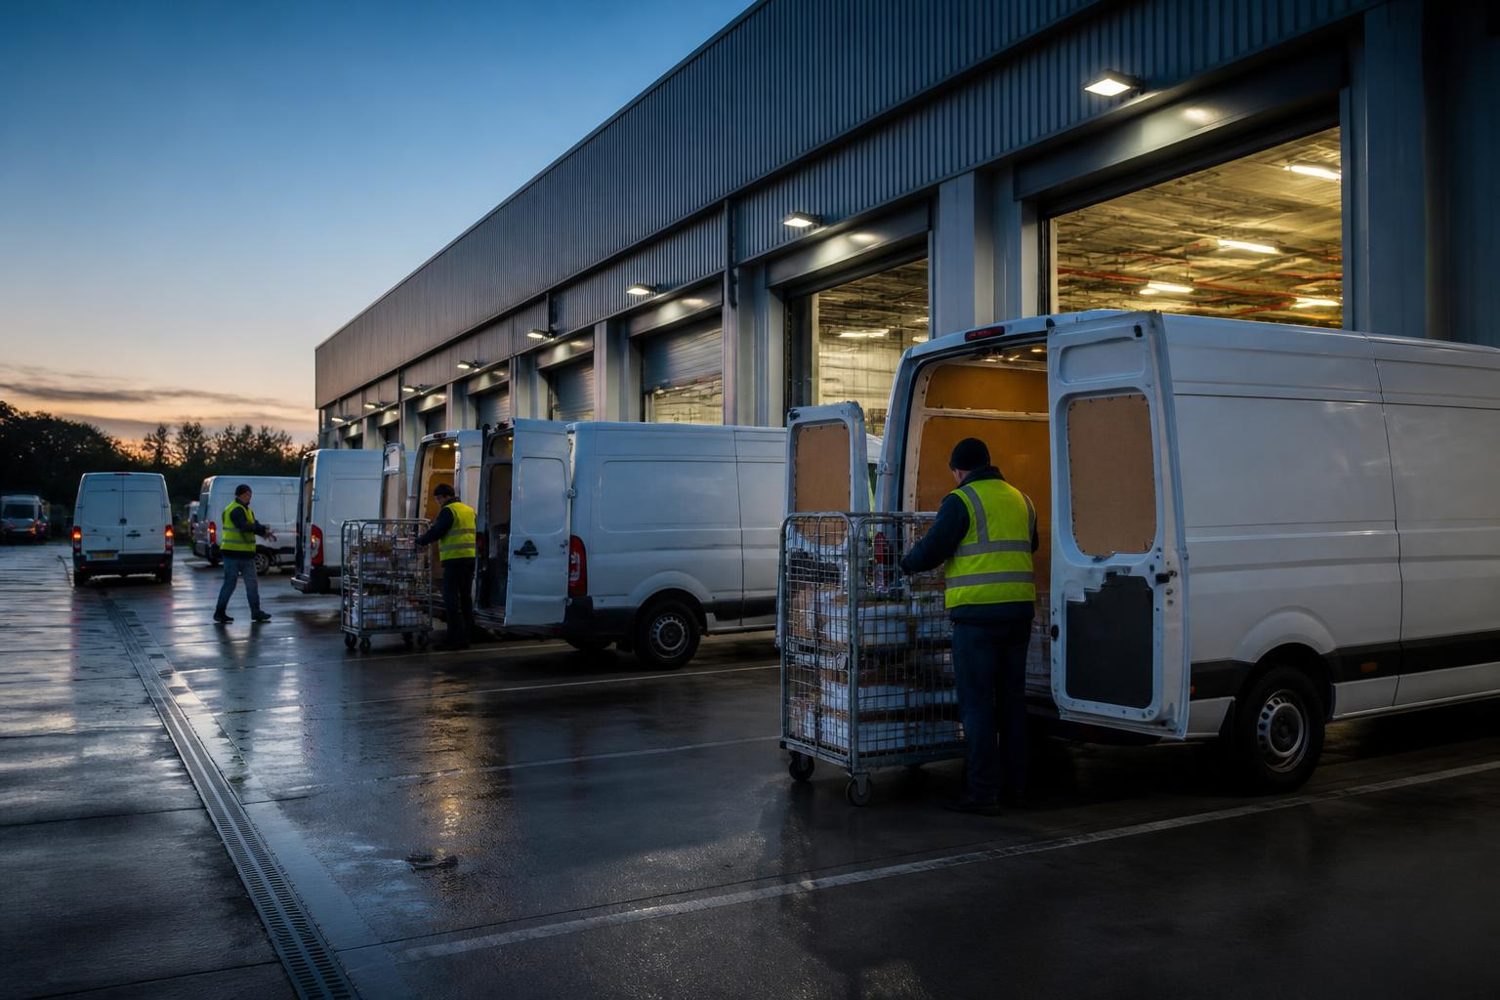
Firms that provide vans normally insure them on a fleet or commercial policy that includes hire and reward use for their drivers. That policy covers the van and liability to others while you work, subject to its own conditions.
What is often covered
Damage to the van, injury or damage to other people and property caused by the van, and theft of the vehicle, at the level the firm has chosen.
What may not be covered
Personal use of the van outside work, your own belongings left in the cab, and sometimes incidents where company rules on locking or keys were not followed.
Excess and deductions
Some firms pass an excess or damage charge on to the driver. It is worth reading your contract or handbook to see how this works.
Using your own van means arranging your own cover
If you deliver parcels in your own van, a personal or standard business van policy is unlikely to be enough. Most insurers expect hire and reward use for any paid parcel work.
Many networks and courier firms that use owner-drivers set minimum insurance levels in their contracts, often covering hire and reward, goods in transit and public liability. Some may offer access to cover. Arrangements vary between firms and change over time, so it is worth checking the current terms in the contract or driver app rather than assuming.
Details worth confirming with the firm you deliver for:
- Whether you are expected to arrange your own van insurance or the firm provides it
- Any minimum goods in transit and public liability levels
- Whether cover the firm offers applies only while you are logged in or on a round
- What documents you need to provide, and when they are checked
Network parcel rounds bring their own patterns of risk
Network rounds tend to be multi-drop, with a set area, a high number of stops and tight delivery windows. That brings the usual multi-drop risks: theft while the van is unattended, low-speed knocks and incidents at the door.
Some rounds start and finish at a depot, while others involve collecting parcels from a hub and taking the van home overnight. Where the van is parked overnight, and whether parcels stay in it, can affect both the van policy and goods in transit cover.
Moving between employed and owner-driver work
Drivers often move from a company van to their own, or take extra work in their own van alongside an employed job. The moment you use your own van for paid parcel work, your own policy needs hire and reward use.
The reverse matters too. If you sell your van and move to a company vehicle, your own policy may lapse, along with the no claims bonus you built on it. Some insurers accept company car or van experience as evidence of driving history, so it is worth asking before you need a new policy.
Questions worth asking before you buy van delivery driver insurance
These questions help pin down who covers what before you take on parcel work.
- Is the van provided to me, or am I using my own?This usually decides whose policy applies.
- Does the firm's policy cover me for personal use?Many company van policies are for work use only.
- Does my own policy include hire and reward use?Paid parcel deliveries in your own van usually need it.
- Who covers the parcels if they are lost or stolen?Goods in transit may sit with you or the firm depending on the contract.
- Am I charged an excess if a company van is damaged?Some contracts pass costs on to drivers.
- Where will the van be parked overnight?Overnight location can affect both the van and goods cover.
- Does the policy cover multi-drop rounds?Network parcel work is usually multi-drop, which some policies treat separately.
Van delivery driver insurance questions
Do employed van delivery drivers need their own insurance?
Usually not for the van itself, as the employer's policy normally covers drivers of company vans while working. It is still worth checking the contract for any excess charges and whether personal use is allowed.
Does my employer's insurance cover me if I crash the delivery van?
In most cases the employer's policy deals with the claim, subject to its conditions. Some employers pass the excess on to drivers or take action if company rules were broken. Your contract or handbook usually explains this.
Can I use my own van for parcel deliveries on normal insurance?
Usually not. Normal van insurance, including most business use cover, excludes carrying other people's goods for payment. Parcel delivery in your own van normally needs hire and reward use on the certificate.
Does van delivery driver insurance cover my own belongings in the van?
Personal belongings are often excluded or have a small limit on van policies. Goods in transit covers the parcels, not your own items. It is worth checking both policies if you leave tools or devices in the cab.
Can I take the company delivery van home at night?
That depends on your employer's rules and their insurer's conditions. Some firms allow it, others require vans to return to a depot. Overnight parking can affect cover for both the van and any parcels left inside.
What insurance do I need to deliver for a parcel network in my own van?
Typically hire and reward van insurance, and often goods in transit and public liability at levels set by the network. Requirements differ between networks and change over time, so it is worth checking the current contract or app terms.
Ready to compare van delivery driver insurance?
One form, specialist brokers, no obligation.